An automated loan application can make a decision quickly. A prospective borrower still has to decide whether to send the service a photograph of their identity document. That moment brings together several questions: who operates the service, why it needs the information, and who can help if something goes wrong.
This exploratory case examines a hypothetical lending journey in Mexico using a supplied Prefield simulation summary. Original run exports were unavailable for verification. The themes below describe generated responses reported in that summary; they do not measure Mexican borrowers’ preferences or an actual onboarding result.
The brief: a loan through an AI chatbot
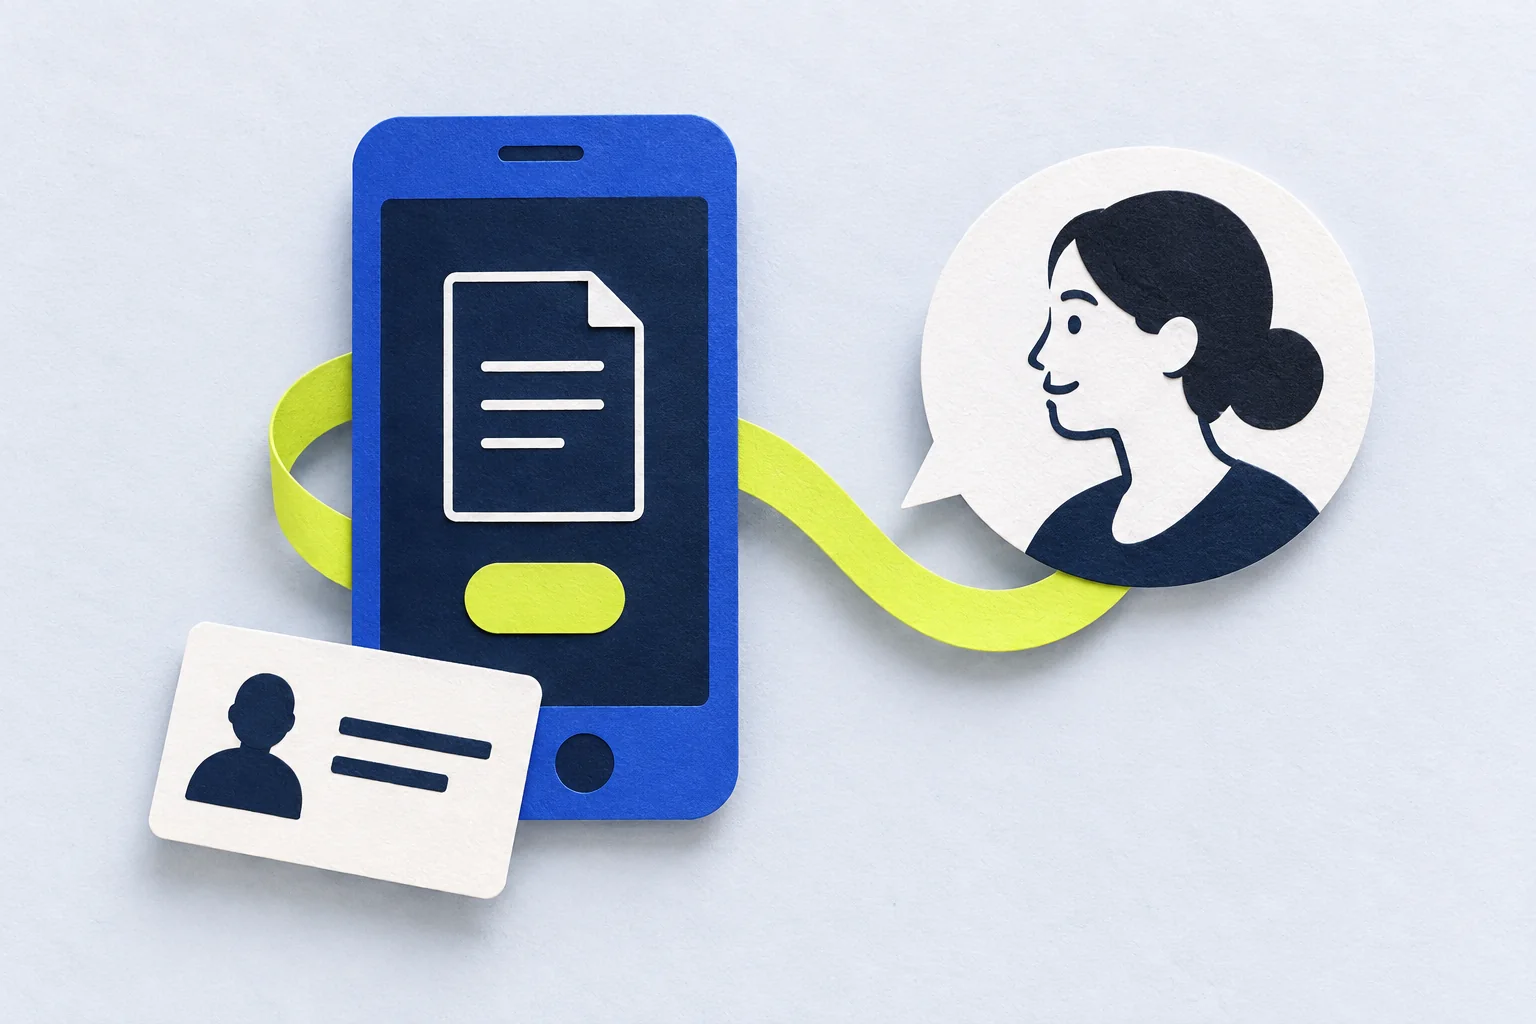
The proposed service offers loans of up to 5,000 MXN. An AI chatbot handles an application at any hour, requests an INE identity document photograph and a selfie, and provides an automated decision. The initial concept has no branch or human support channel. The amount and service design are scenario assumptions.
The summary explores comfort with document submission, preference for speed, reactions to the absence of human support, and interest in a visible route to an agent. It also asks about the underlying need for access to money outside normal banking hours.
Those questions concern different decisions. Needing funds does not establish willingness to use a particular lender. Wanting access to an agent does not show that adding a button increases completed applications. A useful study keeps each outcome separate.
What the simulated responses brought into focus
The identity request needs an explanation. The summary reports generated concerns about misuse of documents and personal information. This suggests examining what applicants understand about the request: its purpose, the operator receiving it, and what happens to their data afterward.
Accountability can be part of the offer. Another reported theme concerns finding someone who can respond to an error or dispute. That is more specific than a general preference for human conversation. A customer might accept an automated application while expecting a reachable person when the process breaks.
Speed may involve a trade-off. The generated responses questioned whether an immediate decision compensated for uncertainty about the provider. Human research should explore when speed matters, what evidence of legitimacy applicants seek, and which problems they would want an agent to resolve.
These themes help shape an interview guide. Fluent wording or familiar local references do not establish how common a concern is, which people hold it, or whether it changes behavior.
The external context: documented lending-app fraud
CONDUSEF, Mexico’s financial consumer protection body, warns about fraudulent loan apps known as montadeudas. Its warning describes offers of easy credit, access to personal information, escalating charges, and threats used for extortion. Read CONDUSEF’s warning about montadeudas.
That source gives the research team a documented reason to investigate fraud concerns. It does not validate the simulation’s response scores or establish that applicants see every automated lender in the same way. A follow-up study should ask about participants’ own experiences and information sources without assuming that fraud is their main concern.
It should also distinguish the service’s actual protections from how clearly those protections are explained. Better copy can help people understand an existing practice. It cannot supply a support process, data protection measure, or complaint route that the service does not provide.
Make the proposed change operational
The most useful product hypothesis is specific: a clear explanation of the operator and document request, together with a functioning support route, may help eligible applicants make an informed decision about proceeding.
That hypothesis has costs and practical requirements. Before testing a human contact option, define who answers, which problems they can resolve, how long applicants should expect to wait, and what happens outside staffed hours. A button that leads to another automated loop would test a different experience from the one promised.
Record the lending terms in the brief as well. Price, repayment schedule, eligibility, and the provider’s identity could affect a decision independently of the interface. Leaving them vague makes it harder to interpret either generated responses or customer feedback.
What to test with people next
- Interview around a recent decision. Recruit people with relevant experience of considering digital credit, including those who abandoned an application. Ask what they checked, where they hesitated, and how they sought help. Do not collect identity documents.
- Walk through a prototype. Use dummy documents and ask participants to explain who receives the information, why it is requested, and how they would resolve a mistake. Observe comprehension and navigation before asking for opinions.
- Compare a defined change. Hold the operator, offer, and eligibility constant when evaluating clearer explanations or support access. Specify the primary outcome in advance and track comprehension, abandonment, help requests, and resolution alongside completion.
More completed applications alone would leave an important question unanswered: did people understand the agreement and the data request? This case makes trust and accountability concrete enough to investigate. The next study must establish which changes help actual applicants and whether the service can deliver them.